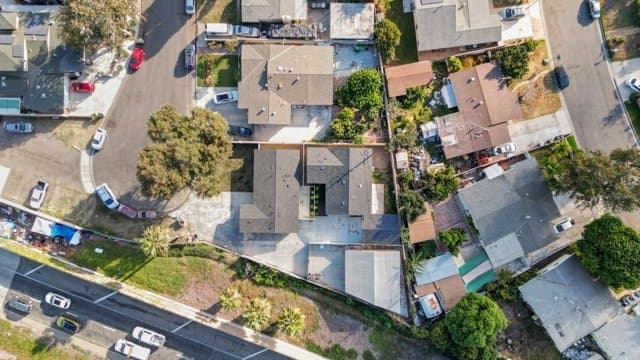
House hacking means living in one part of an income property and renting out the rest, so that tenants help cover the cost of owning. At 13611 Glenhaven Dr in Garden Grove, the layout makes that idea easy to picture: a 3 bedroom, 2 bath main house for the owner, plus a 2023-built ADU and a studio that currently produce $5,200 per month in rent. This guide explains the strategy and shows how to run the numbers for yourself.
The Setup
The estate is offered at $1,728,000. It contains three units:
- Main House (13611 Glenhaven): 3 bedrooms, 2 baths, about 1,200 square feet, with 9-foot ceilings. Currently leased at $3,400 per month.
- ADU (13615 Glenhaven): 4 bedrooms, 2 baths, about 1,200 square feet, built in 2023. Leased at $3,800 per month.
- Studio: studio layout with 1 bath. Leased at $1,400 per month.
In a live-in scenario, an owner occupies the main house, and the ADU and studio together bring in $3,800 plus $1,400, which equals $5,200 per month. Because the units are currently leased, an owner would need to review the lease terms to understand when the main house would become available for occupancy.
The Idea of Net Living Expense
The key number in house hacking is your net living expense. It is simple to define:
Net living expense = total monthly cost of owning the property, minus rental income collected.
The total monthly cost includes your loan payment, property taxes, insurance, maintenance, and any reserves. The rent you collect offsets that cost. What remains is what you effectively pay to live there.
An Illustrative Example
Suppose, purely for illustration, that all-in monthly ownership costs came to $9,000. This is an assumed number, not a quote and not a property fact. Actual costs depend on your down payment, loan terms, tax bill, and insurance.
- Gross rent from ADU and studio: $5,200.
- Assume 5 percent set aside for vacancy and turnover: $260.
- Effective rent: $4,940.
- Net living expense: $9,000 minus $4,940 equals $4,060 per month.
Without the vacancy assumption, the same example gives $9,000 minus $5,200, or $3,800. Changing the starting figure changes the outcome, so the exercise is only useful when you replace the assumptions with your own. If your all-in cost were $7,500, the same math would give $7,500 minus $4,940, or $2,560.
Things That Change the Math
Several factors move the result in either direction:
- Down payment and loan type: a larger down payment lowers the monthly payment. Owner-occupant financing can differ from investor financing, so speak with a lender about what applies to a property with several units.
- Property taxes and insurance: these vary by purchase price and coverage, and buyers should verify them.
- Maintenance and reserves: three structures mean more systems to maintain, so a realistic reserve is wise.
- Vacancy and turnover: a rented unit can sit empty between tenants, so conservative buyers plan for it.
- Utilities: the property has 2 electric, 2 gas, and 1 water meter. Buyers should confirm how those are assigned among the units.
Lifestyle Considerations
Living on the same lot as your tenants is a different experience from owning a rental across town. You will be present when something breaks, which can be a convenience or an obligation depending on your preference. Zero HOA fees mean fewer outside rules, and low-maintenance landscaping keeps yard work modest. You also keep full control of how you handle landlord responsibilities, or you can hire a property manager.
Risks to Keep in Mind
A house hack ties your housing to rental income, and rental income is never guaranteed. A vacancy, a repair, or a rise in expenses can increase what you pay out of pocket. Plan for months when the offset is smaller than expected, and keep an emergency fund. This article is not financial advice, and you should consult a lender and a CPA about your situation.
Calculate Your Net Living Expense
The numbers above are examples, and your own are what count. Contact Global Estate Hub to calculate your net living expense for 13611 Glenhaven Dr, and we will help you build a worksheet with your own assumptions and connect you with a lender for financing questions.